EGT Q3 Update: Repowering Momentum Builds as Drax Contract Adds Long-Term Visibility
Repowering activity continues to convert into completed projects, while a renewed five-year Drax contract and expansion into battery storage add further visibility to EGT’s critical infrastructure growth strategy.
European Green Transition plc has delivered another positive operational update from its Wind Services business, with further progress across repowering, operations and maintenance, remote monitoring and strategic partnerships during the third quarter.
The standout developments are the continued conversion of EGT’s repowering pipeline, the renewal of a five-year O&M contract with Drax Group covering 94 turbines, and a new strategic partnership designed to expand Earthmill’s capabilities into battery storage and energy optimisation.
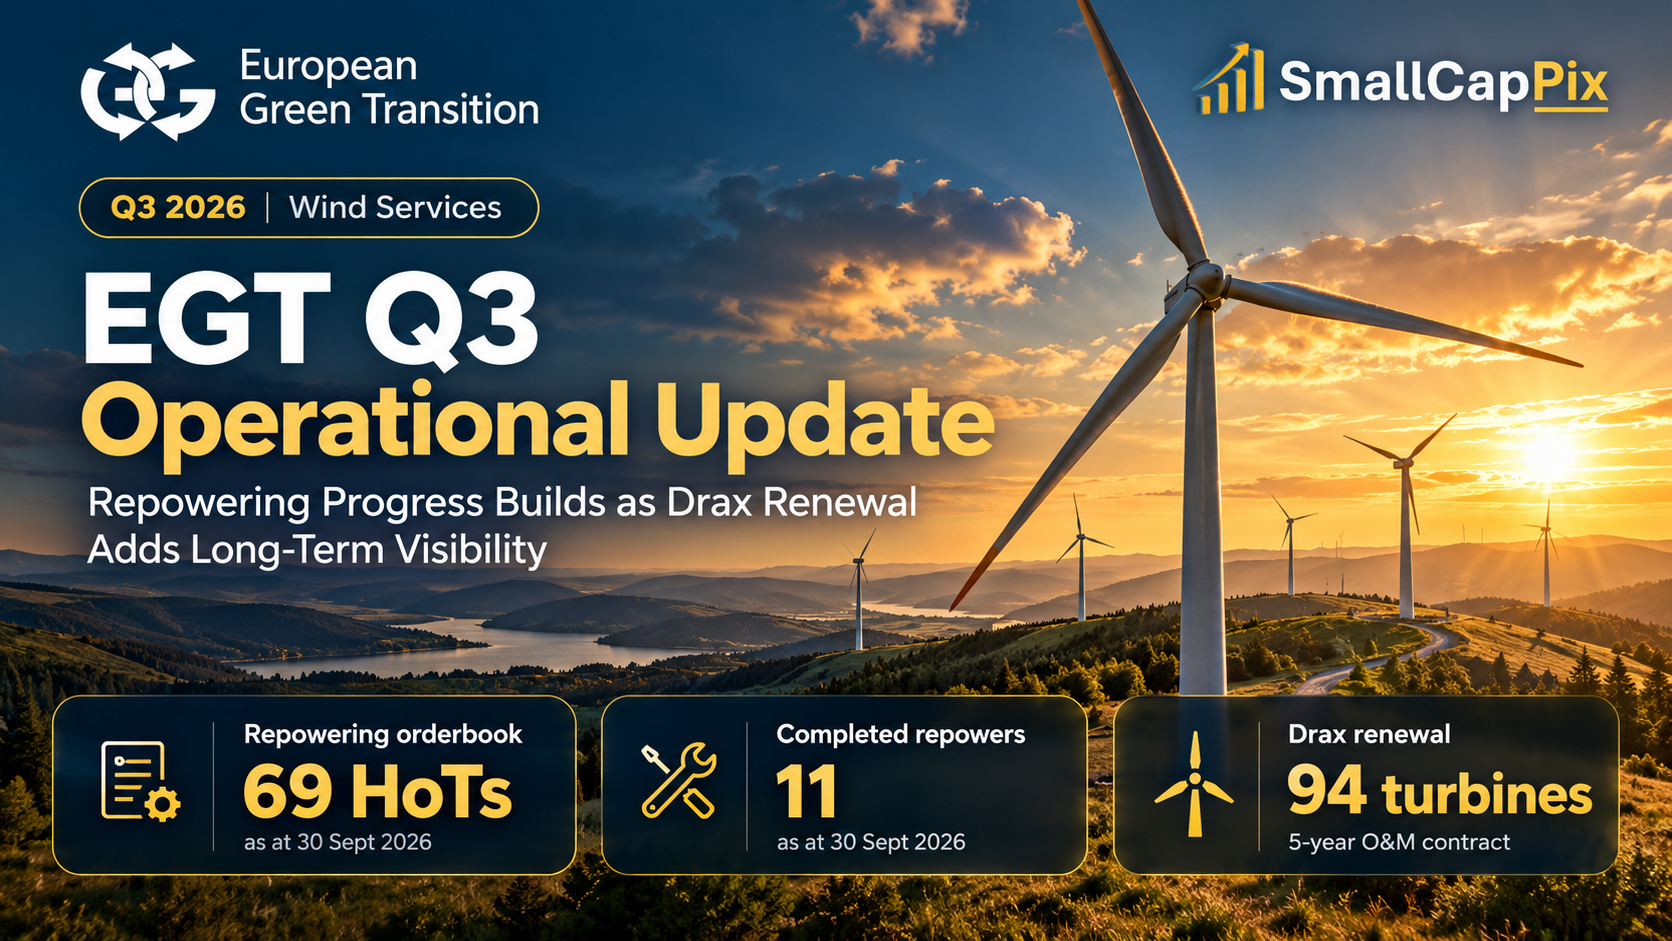
The repowering orderbook has now increased to 69 signed Heads of Terms, with 33 planning approvals, 23 project commencements with deposits received and 11 completed repowers.
With EGT continuing to work across more than 900 turbines in the UK and Ireland and maintaining a potential £126 million repowering opportunity across approximately 280 qualified prospects, the latest update provides further evidence that the Wind Services platform is continuing to scale.
What’s New?
EGT’s Q3 update covers the three months ended 30 September 2026 and shows continued progress across the company’s Wind Services operations.
The business comprises Earthmill Maintenance, Silverford Engineering, Wind Energy Partnership and Anemos Analytics, serving more than 900 onshore wind turbines across the UK and Ireland.
The most important development during the quarter is the continued progression of the repowering pipeline.
During Q3, EGT signed four additional repowering Heads of Terms, secured three additional planning approvals, commenced three more projects with deposits received and completed three further repowers.
That takes the cumulative position to:
- 69 signed Heads of Terms
- 33 planning approvals
- 23 project commencements and deposits received
- 11 completed repowers
The direction of travel is important.
EGT is not simply adding prospects at the top of the funnel. Projects are continuing to move through planning, commencement and ultimately completion.
Repowering Pipeline Continues to Convert
Repowering remains one of the most compelling parts of the EGT growth story.
At the end of Q2, the company had completed eight repowers. By the end of Q3, that figure had increased to 11.
That represents three completed projects during the quarter.
Similarly, projects that had formally commenced with deposits received increased from 20 to 23, while planning approvals increased from 30 to 33.
This gives investors a clearer view of conversion within the pipeline.
The 69 signed Heads of Terms are not the same as booked revenue, and the £126 million potential opportunity should not be treated as contracted sales.
However, the progression of projects through each stage suggests the pipeline is increasingly becoming more tangible.
EGT continues to engage with around 280 qualified repowering prospects across its existing client base of more than 900 turbines.
The company estimates the potential revenue opportunity associated with those prospects at approximately £126 million.
That figure remains one of the largest potential growth drivers within the business.
Drax Contract Adds Revenue Visibility to 2031
One of the most important announcements in the update is the renewal of EGT’s five-year operations and maintenance contract with Drax Group plc.
The contract covers 94 onshore wind turbines across Great Britain and Northern Ireland.
The fleet includes Endurance E-Series and X-Series, Vestas and WTN turbines.
The relationship with Drax originally began in 2021, and the new agreement extends it through to 2031.
This matters for several reasons.
Firstly, it demonstrates customer retention.
Renewing a five-year contract with a major energy operator provides evidence that EGT’s service offering is delivering sufficient value for a customer to commit for another extended period.
Secondly, it provides longer-term revenue visibility.
Repowering projects can generate higher-value growth opportunities, but recurring O&M contracts can provide a more predictable underlying revenue base.
That mix of recurring service income and larger project-driven revenue could become increasingly important as EGT scales.
Earthmill Expands Into Battery Storage
A potentially significant new strategic development is Earthmill’s partnership with a battery storage and energy optimisation provider.
No financial details have yet been disclosed, so it is too early to quantify the impact.
However, strategically the move makes sense.
Battery storage is increasingly becoming part of the broader renewable energy infrastructure ecosystem, particularly as intermittent renewable generation increases.
For turbine owners and energy users, the ability to combine renewable generation with storage and optimisation can potentially improve energy economics and grid flexibility.
For Earthmill, the partnership could broaden the services it can offer existing customers.
That is particularly interesting because EGT already has relationships across more than 900 turbines.
Rather than entering the battery market from a standing start, the company may be able to introduce additional services into an established customer network.
That potentially creates a useful cross-selling opportunity.
Anemos Analytics Continues to Grow
Anemos Analytics also continued to expand during the quarter.
Its contracted turbine base increased from 133 turbines at the end of H1 to 136 turbines at the end of Q3.
The increase itself is relatively modest, but the strategic rationale remains attractive.
Anemos provides predictive condition-monitoring technology designed to help turbine operators reduce operating costs, improve uptime and extend asset life.
This creates another recurring service relationship with turbine owners.
It can also strengthen the wider EGT ecosystem.
Monitoring can identify maintenance requirements, maintenance relationships can lead to repair work, and older assets may eventually become repowering candidates.
That ability to provide services across several stages of a turbine’s lifecycle remains one of the more interesting aspects of the EGT model.
Why It Matters
The key takeaway from the Q3 update is that EGT’s Wind Services acquisition continues to show operational momentum after a strong first half.
The previous interim results gave investors their first look at the financial characteristics of the business, including a gross margin of approximately 26%.
This update provides further evidence on execution.
The repowering pipeline is progressing.
Projects are being completed.
Long-term O&M contracts are being renewed.
The monitoring business continues to grow.
And the company is beginning to expand into adjacent infrastructure services such as battery storage and energy optimisation.
Taken together, this supports EGT’s ambition to become a broader critical infrastructure and renewable services platform rather than simply a wind maintenance business.
The £50 Million Revenue Target
Management has again reiterated its medium-term target of £50 million of Group revenue.
The route towards it is becoming easier to identify.
Organic growth could come from:
- converting more of the £126 million repowering opportunity
- growing the O&M customer base
- increasing monitoring contracts through Anemos
- cross-selling additional infrastructure services
- expanding into areas such as battery storage
- adding further bolt-on acquisitions
The Drax renewal is particularly useful because it reinforces the recurring revenue side of the model.
If EGT can combine that recurring service base with higher-value repowering projects and selective acquisitions, it could create a considerably larger infrastructure services platform over time.
What Investors Should Watch Next
The next important question is how quickly EGT can convert its expanding pipeline into revenue and earnings.
The company has already demonstrated progress from Heads of Terms through planning approvals and project commencements to completed repowers.
Investors should therefore continue to watch the rate of conversion between each stage.
The battery storage partnership is another area worth monitoring.
At present, the commercial significance is unclear.
Future updates will hopefully provide more detail on contract wins, revenue potential and whether battery services become a meaningful additional revenue stream.
The Drax renewal also provides a useful reference point for the quality and durability of EGT’s O&M business.
The SmallCapPix Take
The Q3 update strengthens the EGT investment case without relying on one big headline number.
Instead, several parts of the business are moving in the right direction at the same time.
The repowering orderbook has increased from 65 to 69 Heads of Terms.
Planning approvals have risen from 30 to 33.
Projects with deposits received have increased from 20 to 23.
Completed repowers have risen from eight to 11.
That progression matters because it shows activity moving through the pipeline rather than simply accumulating at the top.
The five-year Drax renewal is also an important validation of the underlying services business.
A contract covering 94 turbines and running through to 2031 adds long-term visibility and demonstrates that EGT is retaining significant customers.
Meanwhile, the battery storage partnership suggests management is beginning to leverage the existing Earthmill customer base into adjacent areas of renewable infrastructure.
There is still plenty for EGT to prove.
The £126 million repowering figure remains a potential opportunity rather than contracted revenue, and investors will want to see continued conversion into completed projects and ultimately cash generation.
But the broader picture is becoming increasingly compelling.
EGT now has recurring O&M revenue, a growing repowering business, monitoring capability, exposure to battery storage and a sizeable installed customer base.
For a company still targeting £50 million of medium-term revenue, the Q3 update provides further evidence that the building blocks are increasingly falling into place.