Living REIT – An 8% Dividend Yield, Discounted Assets and a Potential Rerating Opportunity
With a property portfolio now worth approximately £825 million, an attractive long-term debt structure and a progressive dividend policy, Living REIT could offer investors a combination of income and capital appreciation. Its latest interim results suggest a business making steady financial progress, while a major acquisition could provide the catalyst for accelerating earnings growth. But does the market's discount to underlying asset value represent an opportunity or reflect genuine risks?
Living REIT (LSE: LIVE), formerly known as Social Housing REIT, recently published its interim results for the six months ended 30 June 2026, reporting further growth in rental income, earnings and dividends.
At first glance, the figures might appear relatively uneventful. Net rental income increased by 2.3% to £20.2 million, while adjusted earnings per share rose 2.2% to 3.42p.
However, the more interesting investment story arguably lies beyond the headline growth figures.
The company has completed a significant acquisition that expands its property portfolio to approximately £825 million, diversified into senior living accommodation and inherited attractive long-term fixed-rate borrowing.
Meanwhile, its shares have recently traded around 70p, despite the company reporting net tangible assets of 95.36p per share as at 30 June 2026.
That represents a discount of approximately 27% to the last reported net tangible assets, although this figure predates the July acquisition and therefore does not reflect the enlarged group's updated NAV.
For investors seeking income alongside the potential for a share-price recovery, Living REIT could therefore be worth a closer look.
Key Points
-
Net rental income: Up 2.3% to £20.2 million.
-
Adjusted earnings: Up 2.2% to 3.42p per share.
-
Dividend: Annual target increased 3% to 5.79p per share.
-
Dividend cover: 1.20 times adjusted earnings.
-
Net tangible assets: 95.36p per share as at 30 June 2026, before the July acquisition.
-
Property portfolio: Pro-forma gross asset value of approximately £825 million following July's acquisition.
-
Borrowing costs: Weighted average interest cost of 3.16% following the acquisition, with average debt maturity of 8.9 years.
-
Growth catalyst: Management expects high single-digit earnings accretion from the acquisition in the first full financial year following completion.
The Investment Case for Residential Property
Real estate investment trusts, commonly known as REITs, allow investors to gain exposure to income-producing property assets without directly owning or managing properties.
They are particularly attractive to income-focused investors because qualifying UK REITs are generally required to distribute at least 90% of their tax-exempt property rental profits.
However, the sector has experienced a challenging environment in recent years.
Higher interest rates have increased borrowing costs, pushed up gilt yields and made property income less attractive relative to lower-risk alternatives.
They have also placed pressure on property valuations, as investors demand higher rental yields to compensate for the increased cost of capital.
This creates a potentially interesting situation.
Where a REIT has resilient rental income, long-term fixed-rate financing and a substantial discount to net asset value, improving market sentiment could translate into meaningful capital appreciation.
Living REIT appears to possess several of these characteristics.
The crucial question is whether its property valuations and rental income are sufficiently dependable to justify a narrower discount.
A Growing and Diversified Property Portfolio
Living REIT originally concentrated on specialised supported housing, providing accommodation for vulnerable adults who require additional support to live independently.
These properties are typically leased to registered housing providers, which in turn receive income from housing benefit arrangements and other sources.
The underlying demand for appropriate supported accommodation provides a degree of structural support for the sector.
However, supported housing has also faced difficulties involving the financial strength and operational performance of some housing providers.
Living REIT is now broadening its investment mandate into complementary residential property sectors.
In July 2026, the company completed the acquisition of Residential Secure Income REIT's senior living portfolio for equity consideration of £108.1 million.
The transaction increased the group's pro-forma gross asset value from approximately £648 million to £825 million.
Importantly, this is not simply an exercise in making the portfolio larger.
The acquisition diversifies the business into retirement rental accommodation and reduces its relative exposure to individual supported housing counterparties.
The company's two largest counterparties represented approximately 33.5% of the enlarged portfolio's gross asset value, compared with 40% at the end of 2025.
Management expects the acquisition to deliver high single-digit earnings accretion in its first full financial year.
If achieved, that would represent a noticeable acceleration compared with the modest organic earnings growth reported in the first half.
Why the Debt Structure Could Be a Significant Advantage
One of the most interesting aspects of Living REIT's investment case is its borrowing structure.
Property companies frequently rely on debt to finance acquisitions, making interest costs a major influence on profitability.
A company refinancing substantial borrowings at significantly higher interest rates can experience pressure on earnings and dividend cover.
Living REIT is in a relatively advantageous position.
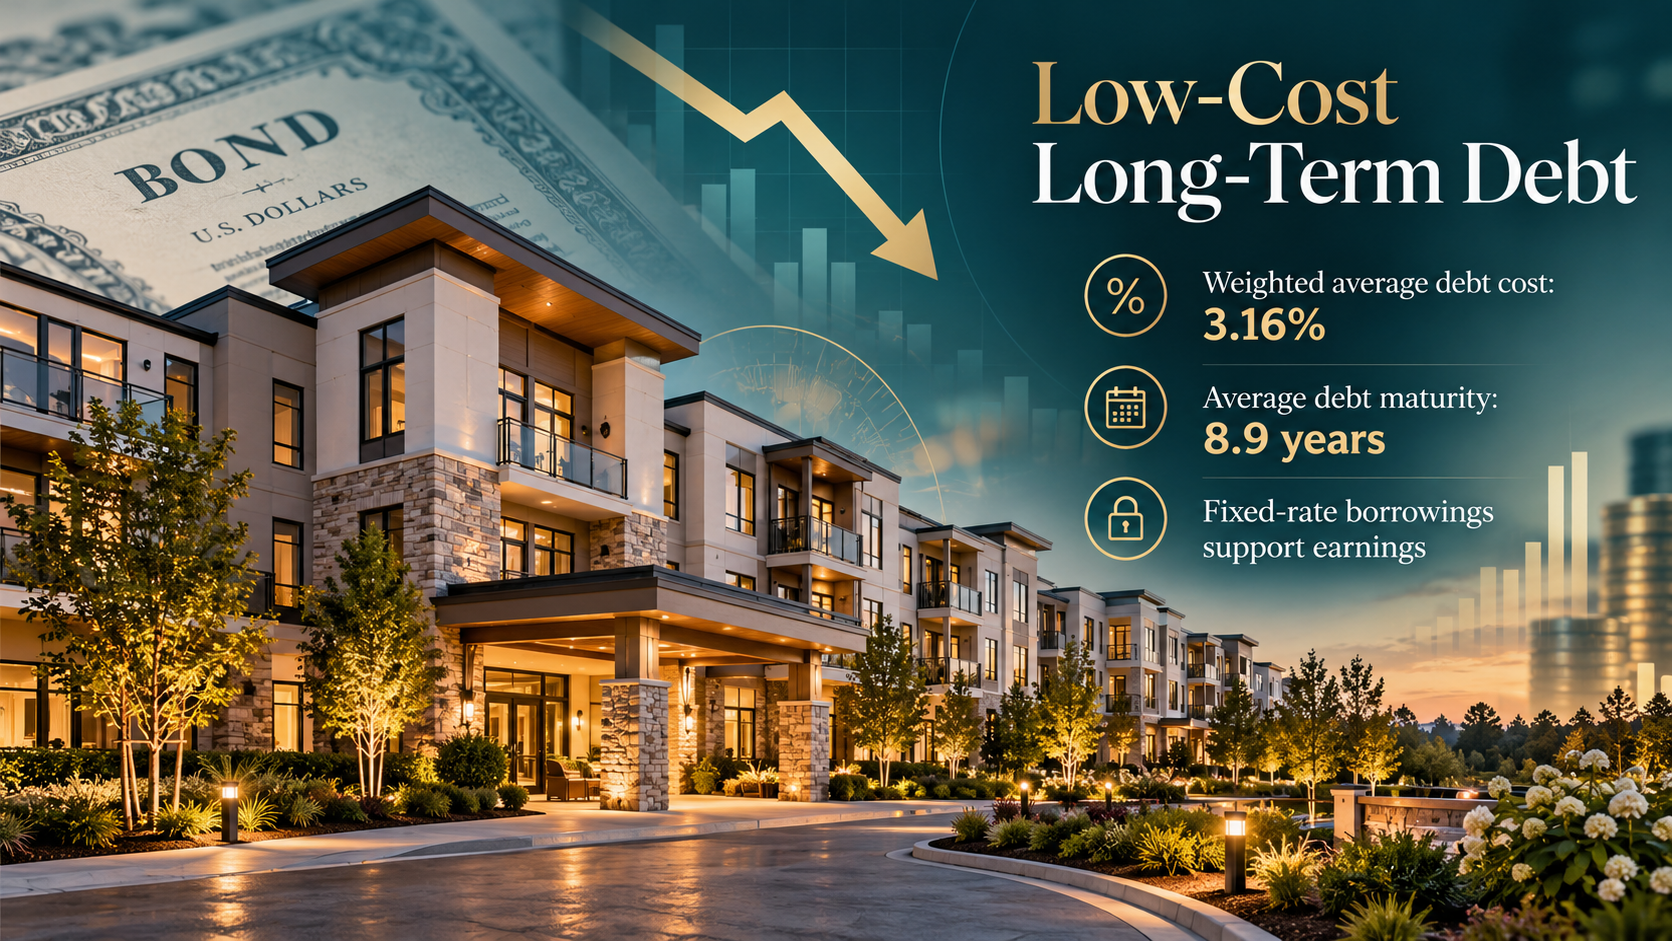
Its existing Barings and MetLife financing totals £263.5 million at a blended interest cost of just 2.74%, with a weighted average remaining term of 7.1 years at the interim reporting date.
The senior living acquisition brought an additional £92.1 million of Scottish Widows debt, with a fixed interest rate of 3.46% and maturities extending to 2043.
Following the acquisition and new Barclays borrowing, the enlarged group's weighted average debt cost stands at approximately 3.16%, with an average maturity of 8.9 years.
In an environment where new property borrowing can be considerably more expensive, access to this financing is a meaningful advantage.
There is also an interesting valuation consideration.
Because much of the debt was secured at historically attractive rates, its economic value differs from the amount recorded on the balance sheet.
Indeed, Living REIT's June accounts reported an EPRA Net Disposal Value of 107.92p per share, compared with EPRA net tangible assets of 95.36p.
This alternative measure includes an approximately £49.4 million adjustment relating to the fair value of debt.
It is not additional cash available to shareholders, nor should investors assume this value can immediately be realised.
Nevertheless, it illustrates how long-term borrowing arrangements can influence the underlying economics of a property investment.
Both these NAV measures relate to 30 June 2026, before the senior living acquisition.
An Attractive Dividend While Investors Wait?
Income is another central part of the Living REIT investment proposition.
The company has increased its targeted annual dividend by 3% to 5.79p per share for 2026.
At an illustrative share price of 70p, that equates to a prospective dividend yield of approximately 8.3%.
For comparison, an investment of £10,000 at that price would generate approximately £827 in annual gross dividends, assuming the target distribution is achieved and maintained.
There is an important difference between a high dividend yield supported by recurring earnings and one that simply reflects an unsustainable distribution.
Living REIT reported adjusted dividend cover of 1.20 times for the first half of 2026.
This suggests that its adjusted earnings currently provide a reasonable buffer above distributions.
If the senior living acquisition delivers its expected earnings accretion, there could be further scope to strengthen dividend cover or support progressive dividends.
Of course, the dividend is not guaranteed.
Rental arrears, property valuation pressures, financing costs and operational difficulties could all affect future distributions.
But investors are potentially receiving a substantial income return while waiting for the wider investment thesis to play out.
Why It Matters – Could the Shares Rerate?
A dividend yield above 8% is attractive, but the possibility of capital appreciation makes the story more interesting.
Living REIT's latest interim results reported EPRA net tangible assets (NTA) of 95.36p per share as at 30 June 2026, compared with 94.23p at the end of December 2025.
With the shares trading around 70p, this represents a discount of approximately 27% to the last reported NTA.
Importantly, this valuation predates the company's transformational senior living acquisition completed in July 2026, meaning the enlarged group's asset backing and NAV per share may differ from these reported figures.
Nevertheless, the valuation provides a useful reference point when assessing the potential opportunity.
If the shares eventually traded at 85p, that would represent approximately 21% capital appreciation from 70p.
A return to 95p would imply approximately 36% upside, before accounting for dividends.
These are mathematical illustrations, not share-price forecasts. They also assume that the company's underlying asset valuations remain broadly resilient.
The company has several potential catalysts that could encourage investors to reconsider its valuation.
First, the senior living acquisition is expected to be earnings-enhancing.
Second, the enlargement and diversification of the portfolio could make Living REIT more appealing to a broader range of institutional investors.
Third, continued dividend growth could attract income-focused shareholders.
Finally, a more favourable interest-rate environment could improve sentiment towards property companies trading at discounts to asset value.
There is no guarantee that these developments will result in a rerating. But they provide identifiable reasons why the market's assessment of the company might change.
What Are the Risks?
The investment case is not without material risks, and the market's discount should not automatically be interpreted as irrational.
Rental collection remains an issue. The company collected 92.7% of contracted rent during the first half, an improvement from 91.4% a year earlier, but still below full collection. Certain registered providers, notably My Space Housing Solutions and Portus Supported Housing, continue to experience difficulties.
Property valuations remain sensitive to interest rates. Higher gilt yields and property investment yields could lead to downward revisions in asset values, reducing reported NAV. Conversely, declining rates might support valuations, although neither outcome is assured.
Borrowing creates financial leverage. Following the acquisition, net loan-to-value is expected to increase to approximately 45%, above management's medium-term target of around 40%. This increases sensitivity to movements in property values.
The acquisition must deliver. The anticipated high single-digit earnings accretion remains a management expectation rather than an established result. Integration, property disposals and operating performance will be important.
These issues provide credible explanations for why investors may demand an unusually high dividend yield and a discount to NAV.
The SmallCapPix Take – Income Today, Potential Rerating Tomorrow
Living REIT presents an interesting investment proposition precisely because it is not dependent on explosive growth or a highly speculative development programme.
It already owns a substantial portfolio of income-producing properties, generates recurring rental income and pays an attractive dividend.
The recent interim results demonstrated steady underlying progress, with increases in rental income and adjusted earnings alongside a further dividend increase.
However, the acquisition of the senior living portfolio potentially changes the growth outlook.
A larger, more diversified asset base, combined with low-cost long-term borrowing, could allow the business to achieve higher earnings without taking on the same refinancing pressures facing some other property companies.
The valuation is particularly interesting.
At an illustrative share price of 70p, investors are buying shares at approximately a 27% discount to the company's last reported EPRA net tangible assets of 95.36p per share, as at 30 June 2026, while receiving a prospective dividend yield of approximately 8.3%.
Although the July acquisition means the enlarged group's NAV per share may now differ from that historic figure, the discount remains a useful starting point for the valuation debate.
If the company delivers the acquisition benefits, improves rent collection and maintains its dividend, there may be a stronger argument for a narrower valuation discount.
There is also a potential longer-term tailwind if interest rates and property yields become more supportive.
Nevertheless, the supported housing tenant issues and increased financial leverage mean the discount is not without justification.
For SmallCapPix, the attraction lies in the combination of substantial income, tangible asset backing and identifiable catalysts for a possible rerating.